

Since my last post, I have been working at a fund researching bank stocks. I learned a lot and hope to demonstrate that over the next year writing this newsletter. Today’s newsletter is a short overview of an interesting bank, but going forward, the plan is to post every Thursday. One of these posts a month will be a deep dive on a company, the others will be earnings updates, financial history posts, and more. I’m very excited to get back into the newsletter writing flow again. Please comment/reply any companies you think I should look into.
Oak Valley Bancorp (NASDAQ: OVLY) is a $2bn asset bank that is the holding company for 19 branches in Northern California. California, in general, has been a gathering place for many small high-quality banks. For example, CalPrivate, California Bancorp, FFB Bancorp, and more. Oak Valley focuses predominantly on CRE lending (90% of their loan book), with most of that in Multi-Family.
Thesis:
Oak Valley Bancorp has a flexible balance sheet that allows management to capitalize on attractive opportunities. Two of the driving factors are their strong, low-cost, low-turnover deposit base and the bank’s impressive asset quality. The bank has strong returns on equity, and the management team has a long tenure and is trained beyond necessity, showing a goal beyond the status quo.
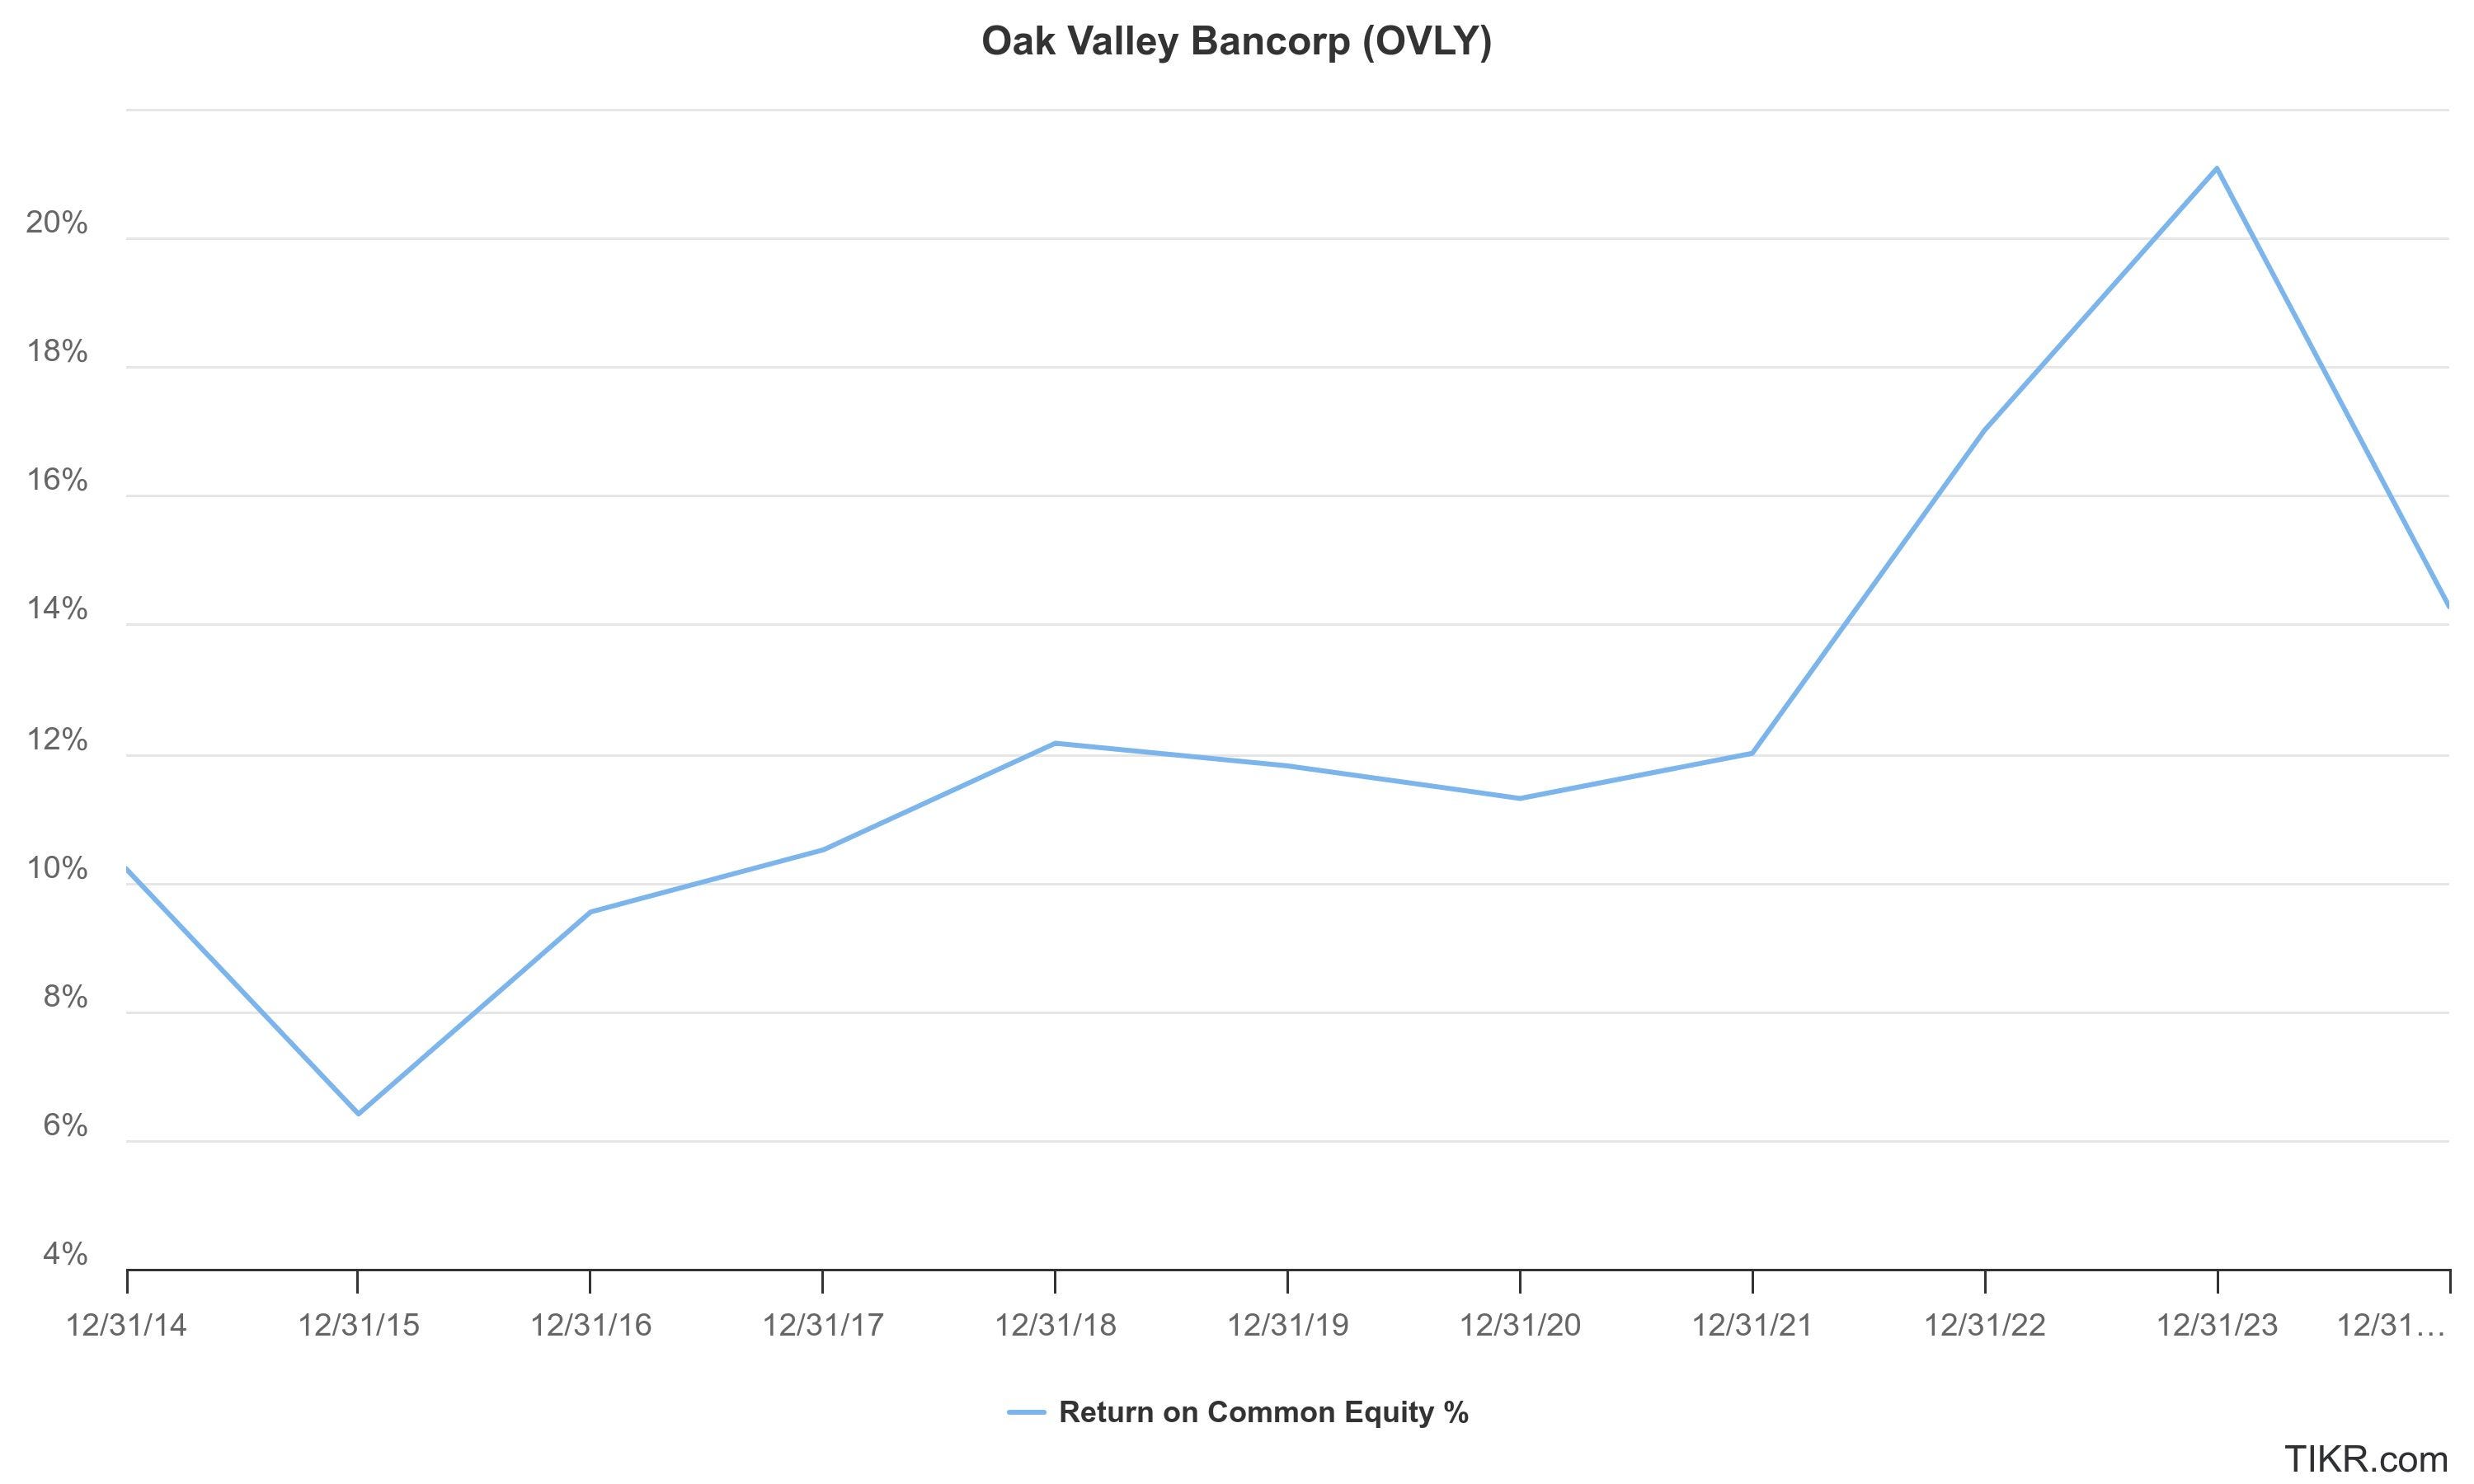
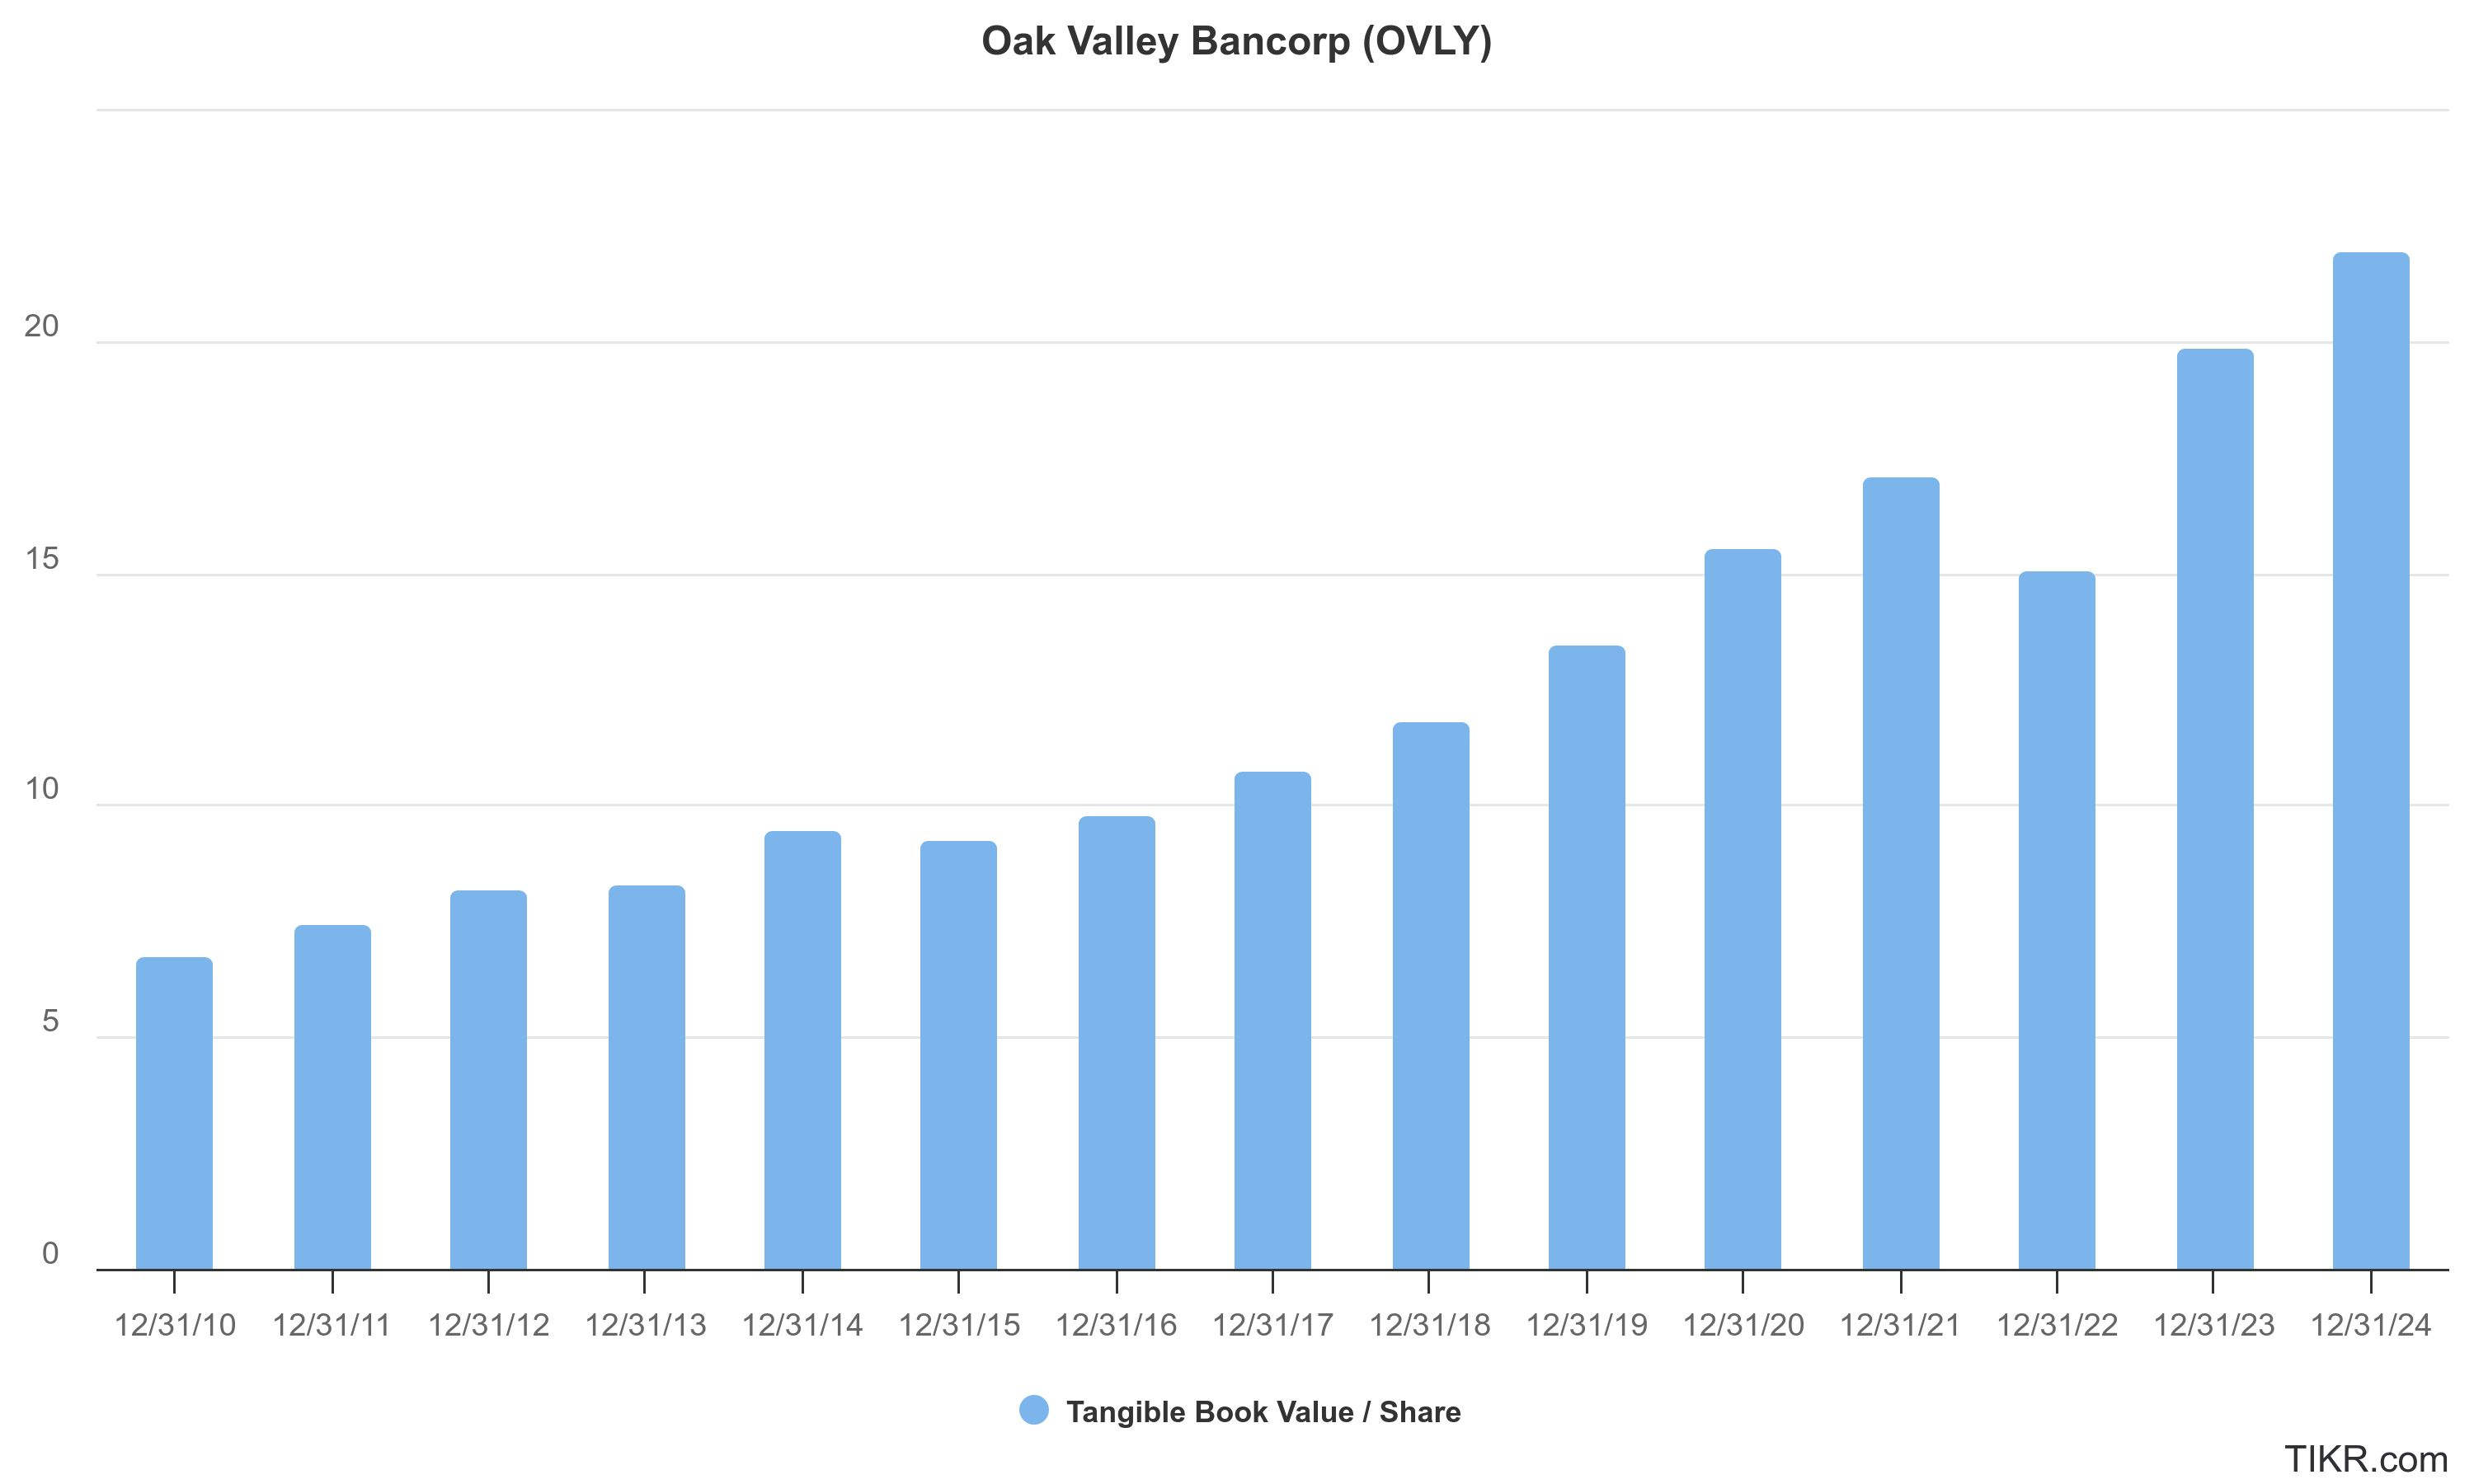
The bank produced a 10% 5-year book value per share CAGR.
Competitive Advantages:
The single biggest competitive advantage for Oak Valley, in my view, is its extremely low cost of funds at just 74 bps in 2Q25. This gives them flexibility on their lending side to maintain quality in less favorable rate environments. The low cost of funds is a function of their local presence. California has proven to be a difficult deposit environment for large banks.
Oak Valley has continued to report extremely impressive asset quality. The only point of concern in the loan portfolio is within consumer lines; however, this only accounts for $33m of the $1.1bn loan book. So far in 2025, the bank has reported 0.003% net charge-offs (NCO) / total assets.
Further within the realm of safety, the bank has CET1 and Total Risk-Weighted Capital Ratios of 14.8% and 15.7%, respectively.
As of 2Q25, the bank has a comfortable 64.9% Loan/Deposit Ratio. The securities portfolio is completely in available-for-sale (AFS) at $503.3bn. This limits the opacity in fair value that can be a factor when holding held-to-maturity securities (HTM). Combine this all with a $198.9bn cash position the bank has one of the best balance sheets I’ve seen.
All of the pieces come together to create a balance sheet that is both safe and high quality. The bank has limited opportunities for risk through, a low loan/deposit ratio, and high regulatory capital. Simultaneously, the bank has built strong quality through a very low cost of funds and very low net charge-offs.
It can be hard to tell from the outside the level of buy-in to a company’s values, but at Oak Valley, there is significant monetary buy-in. The CEO owns 2.82% of the bank, and there are multiple executive team members and board members with over 2% ownership.
On the qualitative side, many of the executive team members have attended banking schools with the CEO, CCO, an SVP, and two EVPs, all being former Pacific Coast Banking School (PCBS) students. I find banking schools to be one of the few easily measurable qualitative areas for better understanding management teams. Further, I am generally biased towards a more favorable view of PCBS and LSU Banking School grads, not to discount any other banking schools. With the high count of executives being graduates, this is an even stronger positive signal. One last note on management, Chris Courtney, the CEO, has been with the bank for almost 30 years, he worked his way from commercial loan officer to CEO.
Risks:
The loan book is always the first concern with a bank. For Oak Valley, this has been a source of strength.
If I were to cite the one biggest concern within the business, in my view, it would be operational inefficiency. The bank has an efficiency ratio of 60.1% in 2024, up from 49.9% in 2023. While efficiency ratio isn’t a comprehensive measure, in this case, it is useful. The bank uses financial efficiency in the form of low-cost deposits and strong earning assets to mitigate this; however, efficiency as a bank investor is one of the more straightforward, attractive attributes to look for.
The banking environment is dynamic on both sides of the balance sheet. For Oak Valley, the bank identifies itself as “slightly sensitive.” The bank doesn’t release specific information about the direct effect of interest rate changes on net interest income (NII). Looking at interest rate changes from recent years it can be observed that interest income is far more sensitive to interest rate changes compared to the deposit base. Both change with interest rates, but deposits in low to no-rate environments go almost to zero for interest expense and up to 80 bps in high-interest-rate environments.
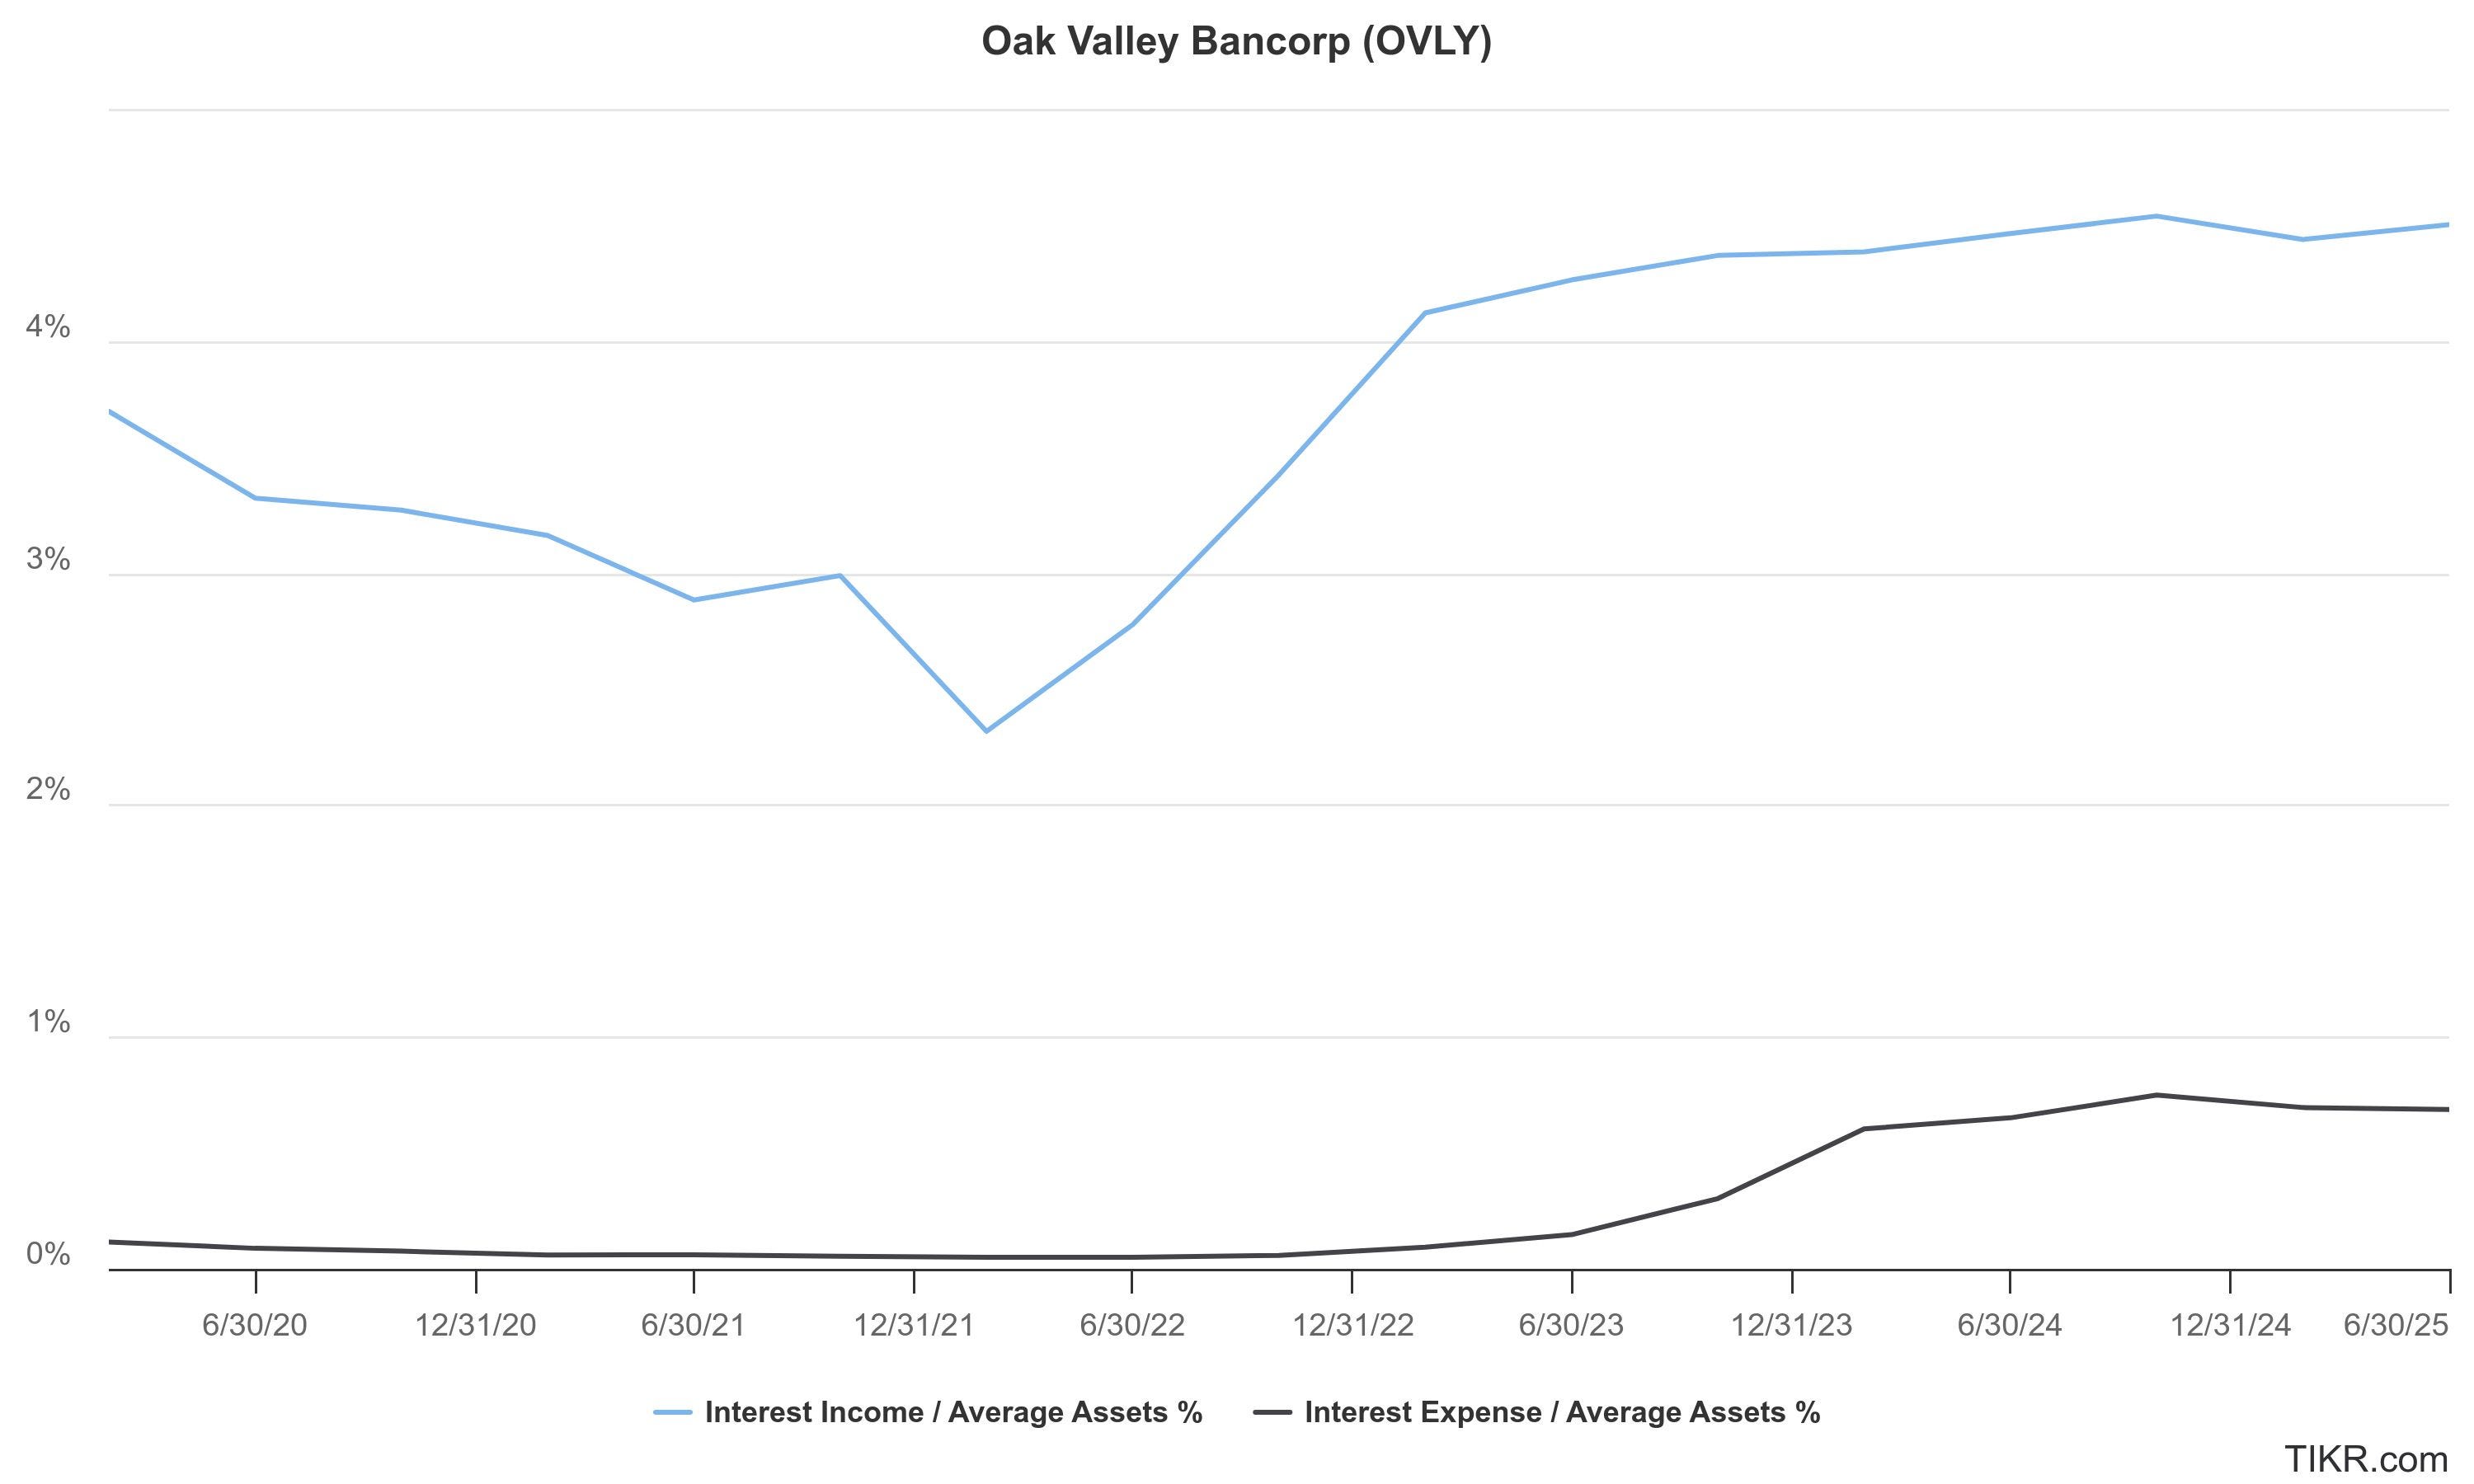
Whereas, interest income/average assets has gone as low as 2.3% in low to no rate environments and as high as 4.5% in high rate. This means that Oak Valley, generally speaking, if favored by higher rate environments, but can still perform well regardless of interest rates due to the low-cost deposits.
“For all of 2024, we were relatively neutral but slightly "asset-sensitive" meaning we expect our net interest income to increase as market rates increase and to decrease as market rates decrease.” - 2024 10-K
Final Thoughts
Oak Valley Bancorp is one of the most interesting banks I’ve looked at. Especially in a current bank investing environment with still partially depressed NIMs and excessive book value multiples, Oak Valley looks like an oasis of strong performance and a reasonable 1.17x Price / Tangible Book Value multiple. This is on the low end of the trading range for the bank and a good value multiple, especially in the context of the current premium multiples throughout the industry.
As the bank continues to expand, opening its most recent branch earlier this year, it should continue to cement its position as an important deposit player in Northern California. However, due to the bank’s already attractive loan/deposit ratio, the bank can meaningfully increase its earning assets without significant deposit growth.
Until Thursday,
Soren
nice work... write up Versabank for me 😉